FEMA, NRE Accounts, and Wedding Payments: What NRI Families Need to Know Before Paying an Indian Vendor
| This article is intended as general orientation, not financial or legal advice. Every family’s situation differs, and we always recommend confirming specifics with a chartered accountant familiar with FEMA regulations before making large payments. |
For many NRI Couple Wedding, the financial mechanics of paying Indian wedding vendors from a foreign bank account is a source of quiet confusion, and rightly so. It sits at the intersection of two systems that were not built to talk to each other easily.
Why This Matters More Than Couples Expect
A ₹1.5 crore wedding involves dozens of vendor payments across venues, décor, catering, entertainment, and logistics. Getting the payment mechanics wrong, using the wrong account type, missing documentation, or triggering unnecessary compliance flags can create real delays at exactly the moments you can least afford them, days before a wedding.
NRE and NRO Accounts, Simply Explained
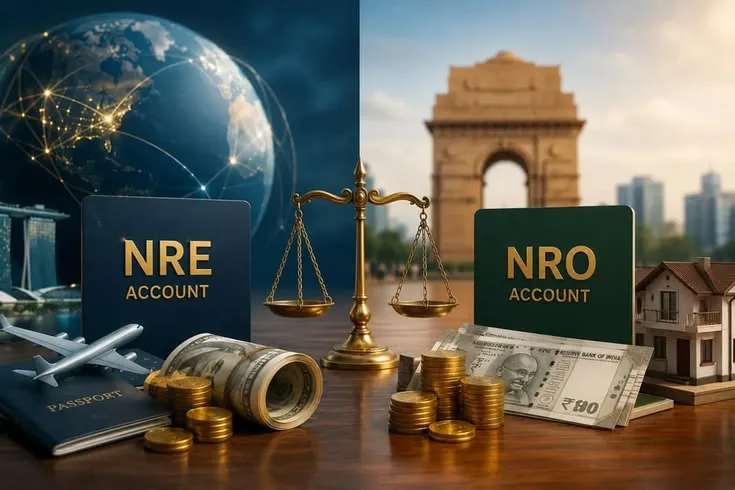
An NRE account, Non-Resident External, holds foreign earnings you bring into India, and both the principal and interest are typically tax-free and fully repatriable. An NRO account, Non-Resident Ordinary, is meant for income earned within India, such as rent or dividends, and carries different tax and repatriation rules. For most Luxury NRI wedding payments, funds are usually routed through an NRE account or transferred directly via international wire, but the right choice depends on where your money sits and how you earned it.
FEMA Basics for Wedding Spending
The Foreign Exchange Management Act governs how money moves between India and the rest of the world. For personal expenses like an NRI Couple Wedding, most straightforward vendor payments do not run into complications. Still, larger sums, multiple currency conversions, and property-related payments, such as long venue buyouts, can sometimes require additional documentation. Keeping clear records of every payment, invoice, and the purpose of each transfer is the simplest way to stay compliant without friction.
How International Payment Gateways Help
A planner or vendor who accepts payments through a proper international gateway, alongside standard wire transfer, removes a significant amount of friction. Look for GST-compliant invoicing on every payment, clear documentation you can share with your accountant, and a planner who can explain, in plain language, what each payment is for and why.
Questions to Ask Your Planner About Payments
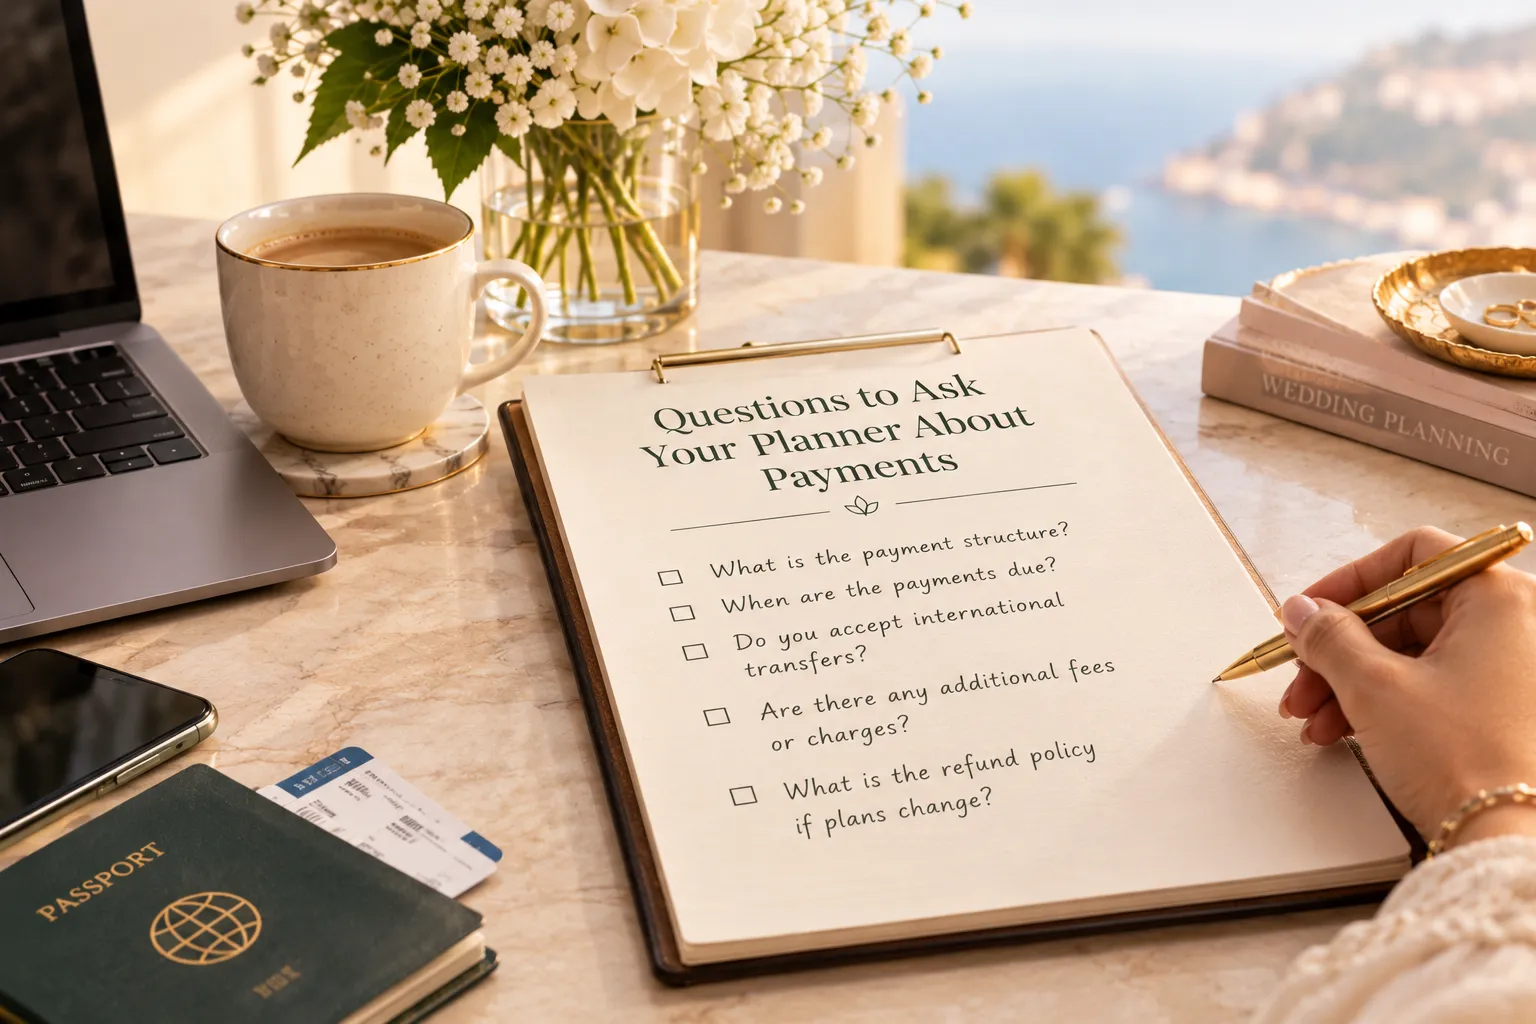
- Do you provide GST-compliant invoices for every payment?
- Can you accept international card payments or wire transfers directly?
- Will you provide a consolidated payment summary I can share with my accountant?
A planner used to working with NRI families should be able to answer these without hesitation. If they cannot, it is worth asking why.
| We work with NRI families across the US, UK, and Gulf regularly, and our finance team can walk you through exactly how payments flow for your specific situation. Get in touch. |
FAQs
1. Can an NRI pay an Indian wedding vendor directly from an overseas bank account?
Yes, an NRI can generally make legitimate payments to Indian wedding vendors from an overseas bank account through permitted banking channels. The payment method and documentation requirements can vary based on the transaction, currency, and vendor. It is advisable to retain invoices, payment confirmations, and other supporting records.
2. Should NRI families use an NRE or NRO account to pay wedding vendors?
The appropriate account depends on the source of the funds and the nature of the transaction. NRE accounts generally hold foreign-sourced income brought into India, while NRO accounts are commonly used for income earned in India. Families should confirm the appropriate account with their bank or a FEMA-qualified professional before making substantial payments.
3. What documents should NRIs keep when making wedding payments in India?
Keep vendor invoices, GST invoices where applicable, contracts or agreements, bank transfer receipts, card payment confirmations, and records showing the purpose of the payment. Maintaining an organised payment trail can make accounting and any future compliance queries easier to address.
4. Do FEMA rules apply to wedding payments made by NRIs?
FEMA governs foreign exchange transactions and the movement of funds involving India. A normal payment for genuine personal wedding expenses may be straightforward, but the applicable requirements can depend on the source, route, amount, and nature of the payment. For significant transactions, professional advice can help ensure the payment is structured correctly.
5. Can Indian wedding planners accept payments from NRI clients through international payment gateways?
Some NRI Couple Wedding planners and vendors can accept international card or online payments through authorised payment providers. Before paying, ask about the available payment method, applicable charges, invoice or GST documentation, currency conversion, and the payment record that will be provided for your financial records.